Monday starts slowly, with nothing significant in terms of scheduled economic events for the FX market. However, traders will pay attention to speeches from ECB President Lagarde and BoC Governor Macklem.
While the chances of these speeches creating significant market volatility are low, Macklem’s remarks will be watched for clues on the BoC’s policy outlook, particularly whether persistent energy prices could raise expectations for a rate hike this year.
Throughout the week, several FOMC members are also expected to deliver remarks, which will be important to monitor for clues about future monetary policy decisions.
On Tuesday, the U.S. will release the ADP weekly employment change and Richmond manufacturing index, while Wednesday will bring flash manufacturing and services PMIs for Australia, the Eurozone, the U.K. and the U.S.
On Thursday, Australia will release its employment change figures and the unemployment rate, while the highlight in Switzerland will be the SNB monetary policy announcement. Canada will release retail sales data, while the U.S. will publish unemployment claims and new home sales.
Finally, on Friday, the U.S. will release durable goods orders m/m, the revised UoM consumer sentiment and the revised UoM inflation expectations. It is also worth mentioning that Japan will have bank holidays from Monday through Wednesday.
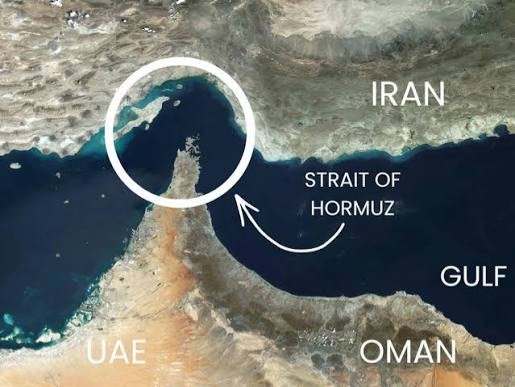
In the Eurozone the focus will be on whether business activity remains stable despite the rising energy prices and increased hostilities in the Middle East between the U.S. and Iran, as well as between Saudi Arabia and Yemen.
In Australia, the consensus for employment change is 20.9K vs. the prior -15.8K, while the unemployment rate is expected to remain unchanged at 4.5%.
After rising in May and June, employment fell by 15K in July, below analysts’ forecasts. However, despite the monthly decline, employment growth had remained relatively solid through the first half of the year, alongside the recovery in economic activity. With headwinds building, Westpac analysts forecast a slower pace of job growth in the second half of the year, with +30K in August.
The unemployment rate edged up only slightly from 4.43% to 4.46% in July, rounding to 4.5%. The drop in employment was partly offset by a 11.7K decline in the labor force, as the participation rate slipped 0.1 ppt to 66.9%. With participation holding around 66.9%, the unemployment rate is expected to remain at 4.5%.
At this week’s meeting, the SNB is expected to keep its policy rate at 0%, with analysts expecting the Bank to remain on hold in the coming quarters. While Q2 GDP surprised strongly to the upside, with growth of 1.5% q/q, half of the increase came from the volatile chemicals and pharmaceuticals sector. The expectation is for GDP growth to slow down in the second half of the year.
Inflation remains subdued, with headline CPI at 0.8% y/y in August and core inflation, which excludes petroleum products, at just 0.3%. The strong franc continues to limit price pressures for imports, which keep inflation under control despite the energy shocks.
Despite some weakening against the euro in recent months, which provided some support to exports, the CHF remains strong by historical standards, ING analysts note. FX intervention remains a backstop against a sharp appreciation of the franc, but systematic intervention is not currently expected.
In Canada, the consensus for core retail sales m/m is -0.5% vs. the prior 0.5%, while retail sales m/m are expected at -0.8% vs. the prior 0.6%. The July retail sales report is expected to reinforce signs that consumer activity started to lose momentum after a strong performance in Q2.
RBC analysts stressed that the underlying picture may be weaker than the headline suggests, particularly after accounting for higher gasoline prices. Early industry data showed a significant drop in vehicle sales in July, pointing to softer consumer spending.
Despite the monthly decline, retail sales volumes are still expected to remain relatively solid on a year-over-year basis, supported by the strength accumulated earlier in the year. In June, volume sales were up around 2% from a year earlier. There are also signs for a recovery in August based on RBC card transaction data and a rebound in auto sales.
In the U.S., the consensus for core durable goods orders m/m is 0.5% vs. the prior 0.4%, while durable goods orders m/m are expected at -0.3% vs. the prior 1.1%.
U.S. durable goods orders are expected to come under pressure in the August data with the report likely affected by a weak set of orders at Boeing during the month. The aircraft manufacturer’s performance is expected to weigh on the overall reading, but the focus will be on how much the Boeing weakness affects the broader headline figure.
The consensus for the new home sales report is 619K vs. 607K prior. New home sales have held up better than resales this year, helped by builder incentives such as price cuts and mortgage rate buy-downs.
However, the rising mortgage rates have eroded that support and new home sales fell 10.5% in July as the average 30-year mortgage rate increased by 20 basis points before leveling off around 6.7% in August.
Buyer traffic remained steady while the share of builders offering incentives was unchanged at 63%, according to the NAHB. Against this backdrop, Wells Fargo analysts forecast a rebound of 2.6% in August to 623K new sales.