France’s public debt has climbed to a record during the two terms of President Emmanuel Macron, unsettling investors and emerging as a defining issue ahead of next year’s presidential election.
With France already gripped by deep social tensions, the candidates vying to succeed Macron are under pressure to explain how they would bring the debt under control. It now stands at 119% of gross domestic product, leaving the country’s strained public finances likely to dominate the campaign.
France again won’t come close to balancing its annual state budget next year, despite a proposed 54 billion euros ($61 billion) in spending cuts. The government said Thursday that the budget will again overshoot EU spending limits and that the national debt is expected to grow to nearly 122% of GDP, a new record.
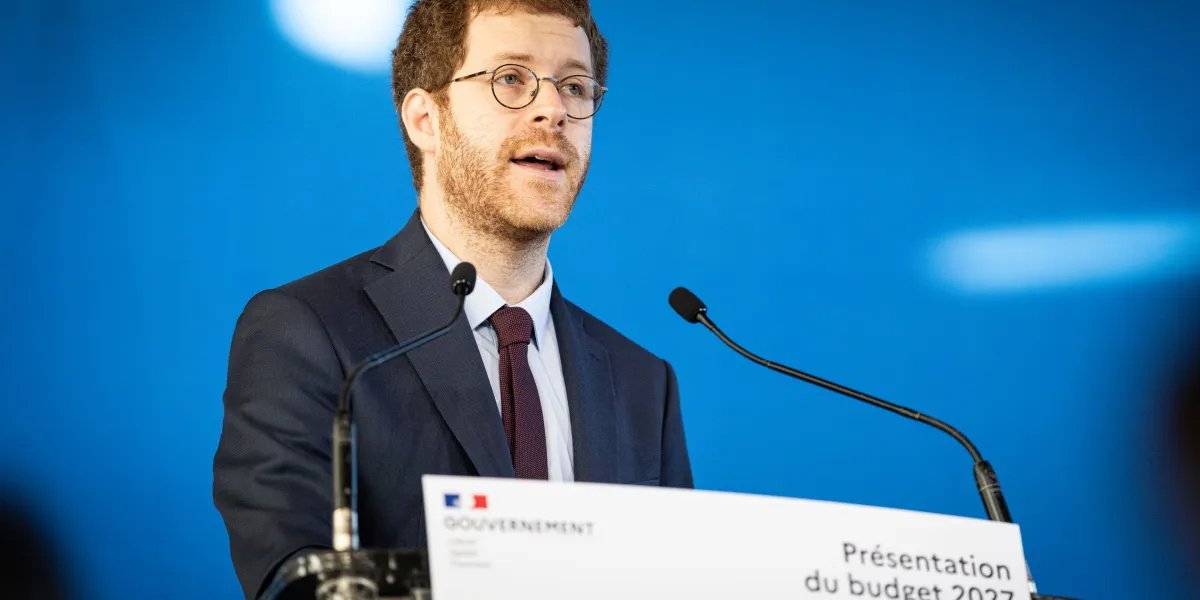
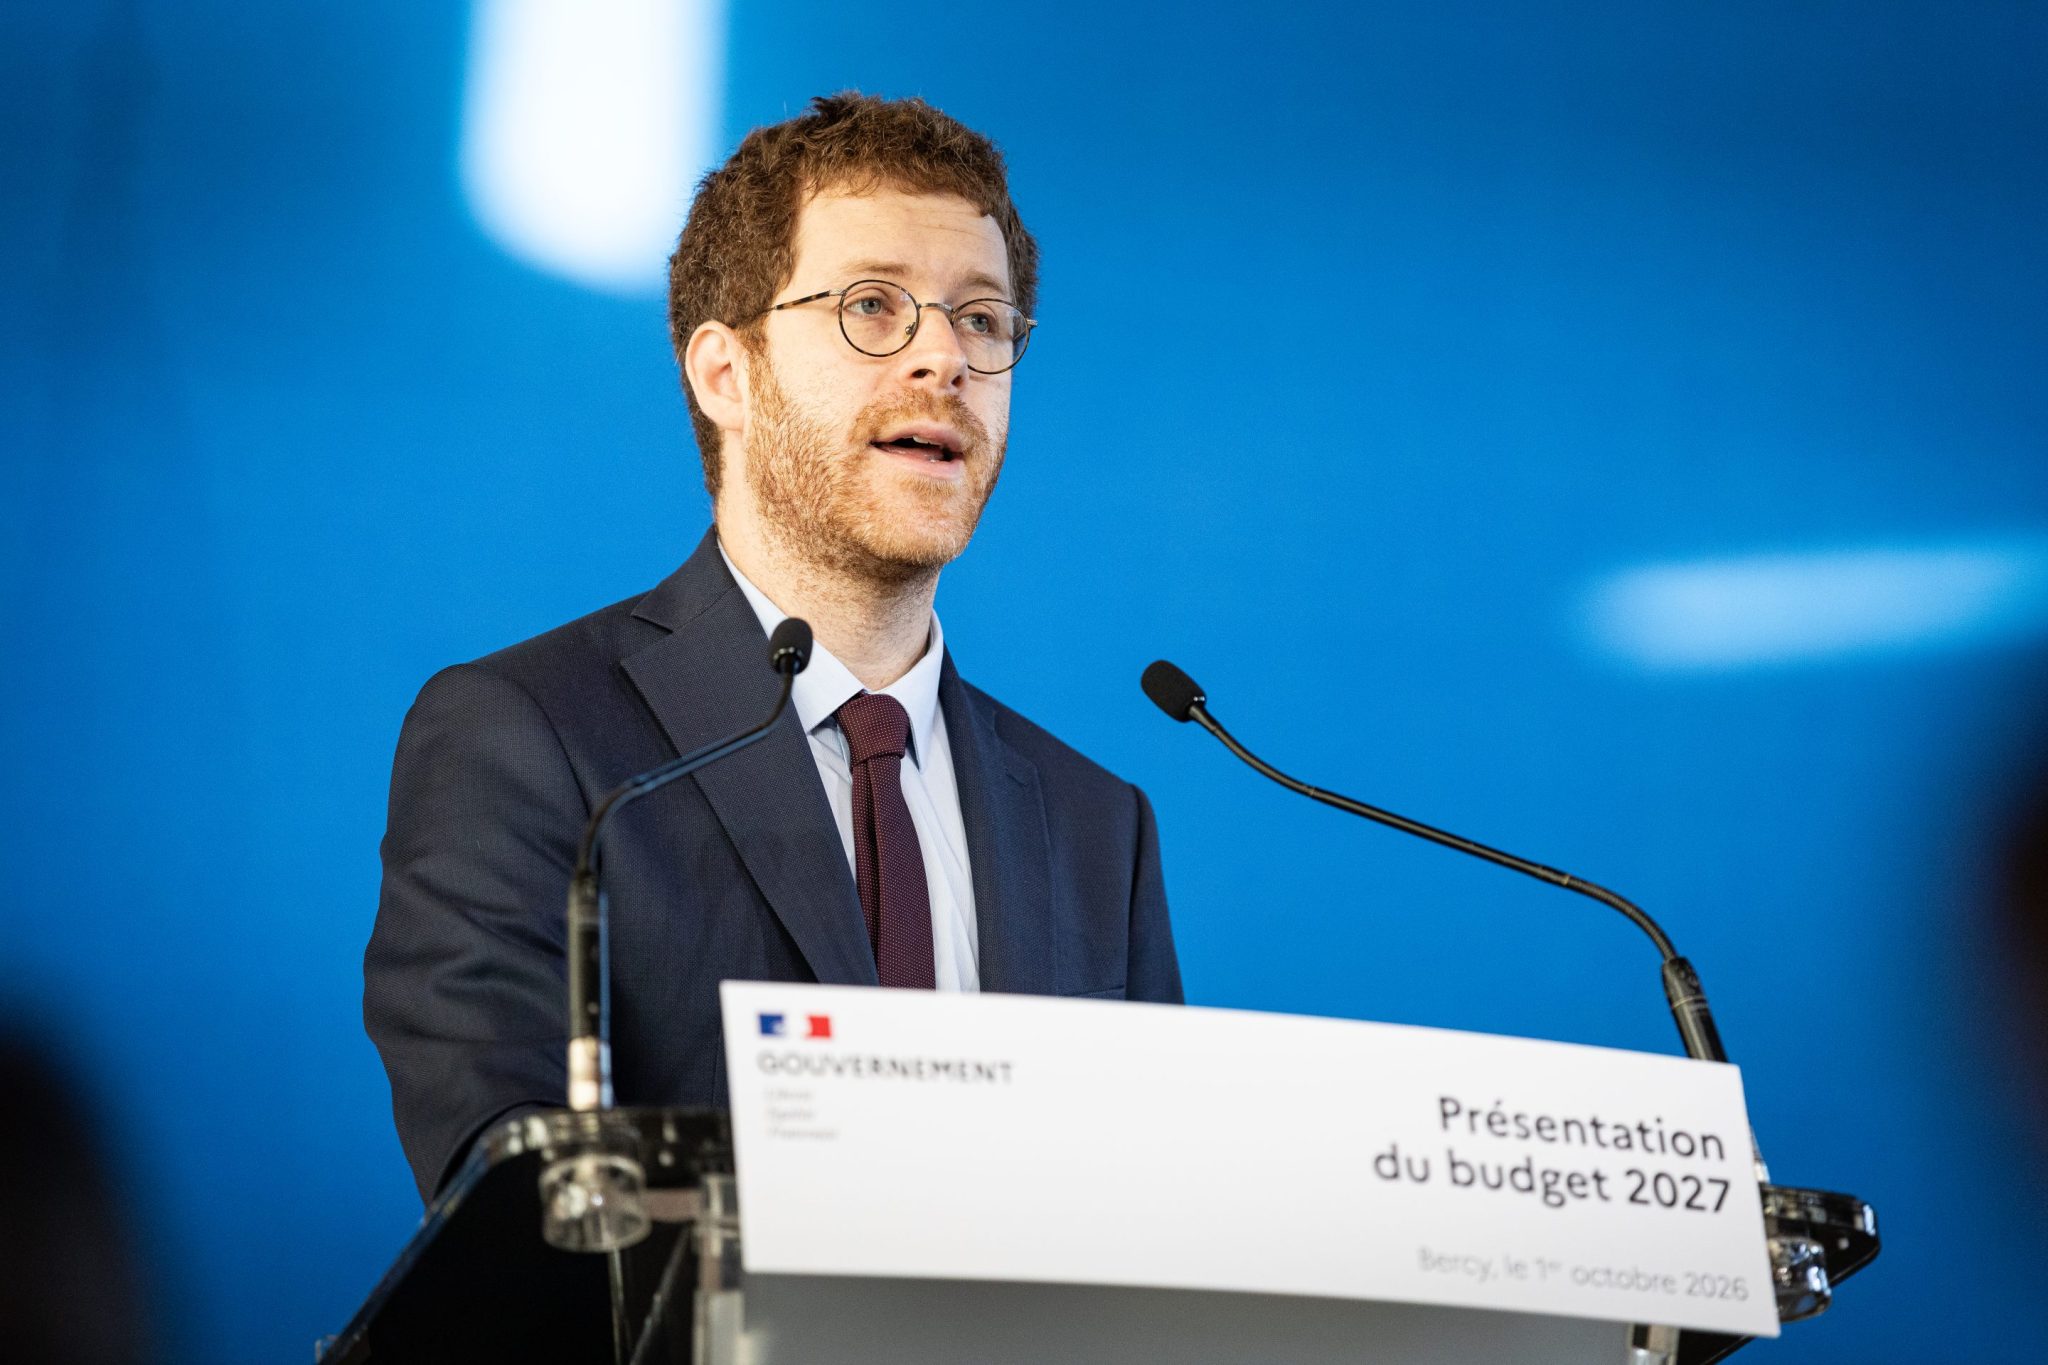
Budget minister David Amiel argued that the spending cuts were essential, ahead of what is sure to be a bruising battle to get them through parliament.
“We cannot sweep the dust under the carpet,” he said.
One idea to fix the debt has been particularly scrutinized. The radical-left presidential candidate Jean-Luc Melenchon has proposed canceling French government bonds held by the European Central Bank to unlock money for public spending, claiming it would free up funds for investment. Others on the right argue that Melenchon’s proposal is unrealistic, with far-right leader Marine Le Pen calling for reforms to “clean up” public finances.
“Freezing this debt means transforming it into perpetual debt — that is, debt with no repayment deadline and a low or zero interest rate,” Melenchon said. “Freezing it is therefore effectively the same as canceling it.”
ECB President Christine Lagarde says Melenchon’s idea would be a “pure violation” of the EU treaty, which bans central bank financing of national governments.
Lagarde insisted that if the country freezes its debt now, the next time it seeks to borrow, creditors could demand exorbitant terms or flat-out say no.
“It’s not because you repeat something that doesn’t make any sense — either legally, technically, or financially — that it becomes something valid,” she said during a Sept. 10 news conference.
Here is a look at France’s public debt and how it affects the second-largest economy in Europe.
Record-high levels
France remains a major industrial power and has the world’s seventh-largest economy. But at the end of June, its public debt stood at 3.596 trillion euros ($4.08 trillion), equivalent to 119% of GDP, according to figures released this week by France’s National Institute of Statistics and Economic Studies.
It stood at 97.9% of GDP in 2019, before the COVID-19 pandemic.
France is hardly alone in loading up on debt in recent years. At the end of the first quarter of 2026, the general government gross debt to GDP ratio in the euro area stood at 88.9%, according to data from Eurostat, the official statistical office of the European Union.
France’s debt pile is smaller than Greece’s, which was 143.5% of GDP, and Italy’s (138.9%). It’s also lower than the U.S.’s 122.6%. France, however, lacks the U.S. advantage of having the world’s dominant reserve currency, which supports Washington’s ability to borrow.
France needs to borrow to finance budgets
Every year, France prepares a budget. These resources mainly come from taxes and levies paid by individuals and businesses. Expenditure is the money used to finance public services such as education, the justice system, or policing. For the past 50 years, expenditure has exceeded revenue, resulting in a budget deficit. To finance this gap and continue funding public services, France takes out loans. The total value of these loans constitutes public debt. Deficits matter because investors demand more in return when they lend the government money.
First the pandemic, then an energy crisis
France last balanced its budget in 1973, while maintaining a generous welfare state with strong worker protections. For years, accumulated debt was high — over 90% of annual gross domestic product from 2008 on — but manageable due to steady growth and years of near-zero interest rates.
Then came the pandemic, followed by an energy crisis after Russia cut off most natural gas supplies following its 2022 invasion of Ukraine. The French government spent heavily on subsidies to keep businesses afloat and shield people from higher energy costs. Globally, interest rates suddenly moved higher. Debt in France jumped from 98% of GDP in pre-pandemic year 2019 to 114% in 2020.
The impact of the debt on France’s budget
As public debt increases, the French state also increases its expenditure. Debt service is a significant item of expenditure, accounting for around 7% of the state budget. With interest rates much higher these days, interest costs are expected to surpass 90 billion euros in 2027, much more than the government plans to spend on defense (63.4 billion) or schooling (65.5 billion).
A stable outlook, but some credit rating agencies are worried
The credit rating agency Scope downgraded France’s long-term ratings in September.
“A sustained deterioration in the fiscal outlook, characterized by rising general government debt, persistently high fiscal deficits and limited progress on structural reforms drive the downgrade,” the agency said in September.
Despite the widening fiscal deficit and rising public debt, Fitch Ratings in August said it is maintaining France’s sovereign credit rating at “A+” with a stable outlook.
“France’s ratings are supported by its large, diversified high-income economy, a sound banking sector and a diverse investor base,” it said.
Who owns French debt
According to France’s economy ministry, French debt is held by a wide variety of investors.
The debt is held by insurers, banks, central banks, and pension funds in countries where retirement is based on funded pension systems.
___
John Leicester in Paris contributed to this report.